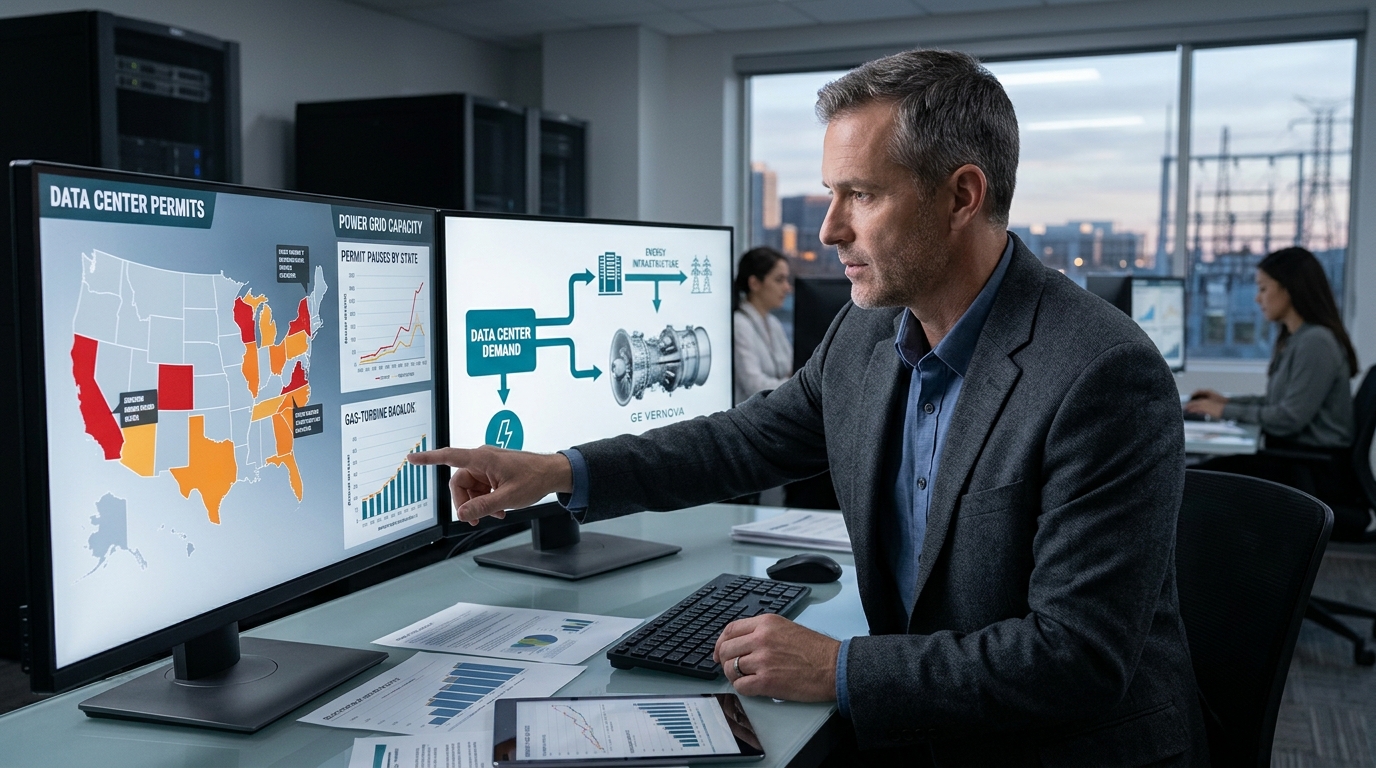
The restriction the market spent months worrying about at the federal level has arrived anyway, state by state. About 40% of the nation’s pending data center capacity sits in states where newly elected governors have pledged to stop or pause approvals, according to data from market intelligence firm Cleanview compiled by Bloomberg. That is not a forecast. It is the map as of this week.
New York and Texas have enacted statewide freezes, pausing key permits or regulatory approvals tied to large data center development. Governor Kathy Hochul imposed a statewide moratorium of up to one year on new hyperscale data centers by temporarily pausing certain state environmental permits while officials develop standards, and the state’s Department of Environmental Conservation said it will not issue discretionary permits not already deemed complete during that period. In Texas, Governor Greg Abbott directed the Texas Commission on Environmental Quality to halt all permits sought by data centers until ERCOT completes an audit, and he also referenced work involving the Texas Water Development Board.
Voters backed limits in dozens of local ballot measures on November 3. In Ohio, Piqua approved a charter change to prohibit data centers above 25 megawatts, and voters also recalled city officials tied to a large proposed Meta project; Sunbury voters approved a 25-megawatt prohibition that put a potential Amazon development on ice. The political direction is not ambiguous.
Why GE Vernova
The conventional read on this week’s news is that it hurts data center landlords and power suppliers. That is partly right. Vistra fell 14% in the post-election session, and investors sold anything tied to the data center buildout. The selloff treated all data center exposure as the same risk. It is not.
GE Vernova (GEV) is a turbine manufacturer, not a landlord or a power producer waiting on a permit. In the third quarter it signed about 11 gigawatts of gas orders and slot reservations, raising the total under contract from 116 to 122 gigawatts, and management said it has already sold delivery slots for 2032. Total backlog reached $197 billion.
The permit freeze actually tightens the economic case for whoever already has sites approved and megawatts locked in. Those customers need power equipment whether permits slow in New York or not, because the demand driving their builds is real and durable. Only about 20% of GE Vernova’s contracted gas turbine capacity serves data centers, which means the company’s earnings are not hostage to any single regulatory wave. The other 80% serves utilities and industrial customers operating well outside moratorium zones.
The Financial Picture
In the third quarter of 2026, GE Vernova reported orders of $29.3 billion, up 96% organically. Revenue reached $12.6 billion, up 27%. Management also said gas orders are being priced about 50% higher per kilowatt than a year earlier. EBITDA margin was 21.4%, up 830 basis points organically. These are not projections inflated by AI optimism. They are contracted numbers from signed orders.
What Could Go Wrong
The stock has not been spared. GE Vernova fell about 10% in the immediate post-election selloff after Democrats won both chambers of Congress, dragged down alongside names whose exposure is far more direct. That dislocation may represent the opportunity, but valuation is not negligible after a year of re-rating.
Any bill curbing data center building would still need President Trump’s signature or two-thirds of both chambers to override his veto, which limits federal risk. State-level freezes, however, need no congressional vote. If moratoriums expand to Virginia, the world’s largest data center market, the trajectory of orders tied to that geography changes. Some estimates suggest state-level actions could delay a meaningful share of planned U.S. data center capacity. GE Vernova’s turbine customers in those markets will face delays.
The Bottom Line
When permit supply tightens, the value migrates to whoever already has the slots. The turbine shortage gives pricing power to whoever owns working megawatts or the factory slots to build new ones. GE Vernova owns the factory slots, with delivery booked into 2032 and a $197 billion backlog that did not shrink when the election results came in. The post-election selloff punished it for a risk it carries only at the margin. That gap between perception and earnings reality is the reason to look at GEV today.