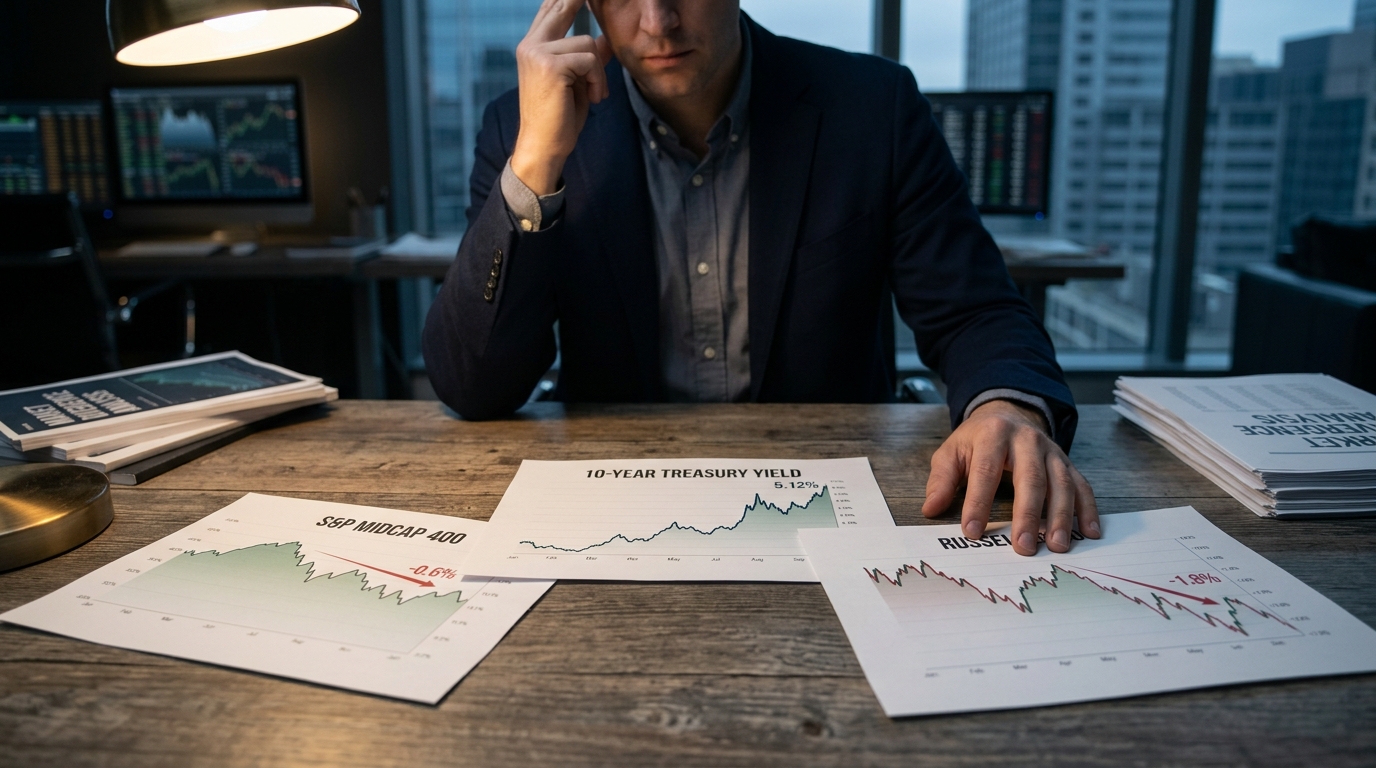
The 10-year Treasury yield does not punish everyone equally. Wednesday’s 15-basis-point surge to 5.12%, its largest single-session move since April 2025, made that clear in the cross-section of equity returns. The S&P MidCap 400 fell 0.6% on the day. The Russell 2000 fell 1.8%. Three times the damage, same bond market, same session.
That divergence is not noise. It is the market telling you exactly where the rate sensitivity lives.
Why the Russell 2000 Has Become a Rate Proxy
IWM’s correlation to the 20+ Year Treasury Bond ETF (TLT) has recently been cited at 0.51, versus 0.29 for SPY and just 0.10 for QQQ. Small caps are now moving in lockstep with long-duration bonds in a way that large-cap indexes are not. The Russell 2000 started September up about 20% for the year. It has since given back a meaningful portion of that move, with year-to-date gains recently cited in the mid-teens, while the S&P 500 is up around 20% and the Nasdaq-100 holds roughly 12%.
The structural reason is debt. Roughly 45% of aggregated Russell 2000 debt is floating-rate, compared to about 9% for the S&P 500. Every hike flows directly and immediately into their borrowing costs. BofA has estimated that each 25-basis-point increase knocks approximately 2% off Russell 2000 operating earnings. With markets still treating another Fed move at the late-October meeting as a live outcome, the arithmetic compounds fast. IWM’s options market has already taken notice: puts outpaced calls in the fund Thursday, while call volume dominated in QQQ.
The Mid-Cap Argument
MDY, the SPDR S&P MidCap 400 ETF Trust, has been up around the low-double-digits year-to-date. That trails the Russell’s headline number but the key distinction is stability under stress. Mid-cap companies occupy a structural middle ground: they are large enough to access fixed-rate bond markets and lock in longer-dated maturities, but still domestically oriented enough to benefit from U.S. economic strength. When the PMI blew past estimates Wednesday and sent yields higher, the MidCap 400 treated it as noise. The Russell did not.
BofA recognized this divide back in late June, formally shifting its SMID preference to mid over small for the second half of 2026. The bank cited the Fed’s hiking path as the core differentiator, warning that small caps carry the most refinancing risk in a continued tightening scenario. Wednesday’s session validated that call publicly and with a three-to-one performance ratio.
Stocks on the Radar: Surviving the Hike Cycle
BofA published a Russell 2000 screen Wednesday identifying quality and value names that have historically outperformed during Fed tightening. The criteria: strong free cash flow, high returns on invested capital, and balance sheets that do not depend on cheap refinancing to stay solvent.
Madison Square Garden Entertainment (MSGE) ranked highly on cash flow returns. The company posted fiscal 2026 revenues of $1.1 billion, up 13%, and adjusted operating income up 18%, driven partly by the Knicks’ championship run. The stock has gained more than 45% this year, BofA holds a Buy and raised its price target to $96, and the business earns its revenue from live events, not from leveraged balance sheet expansion. Rate hikes do not threaten its ticket sales.
First BanCorp (FBP), Puerto Rico’s FirstBank holding company, is a direct beneficiary of higher rates: banks earn more on loans as benchmark rates rise. FBP reported net income of $96.1 million for the first quarter of 2026, up about 25% from a year earlier, and highlighted total loan originations of $1.2 billion in that quarter. Wells Fargo carries it Overweight; multiple services show a recent Wells Fargo price target of $33, while $31 has been cited as a separate target move from another firm in late July.
Risk Dashboard
The primary risk to the MDY-over-IWM trade is a rapid reversal in yields. If incoming data softens and October Fed expectations reprice lower, the Russell’s floating-rate sensitivity becomes a tailwind rather than a liability, and the performance gap closes quickly. The second risk is credit spreads: as long as high-yield stays contained, even the weaker Russell names can refinance. A spread widening changes that calculus in hours, not weeks.
Watch Tuesday’s Conference Board consumer confidence reading and Friday’s PCE for the next yield catalyst. A soft number reopens the rate debate; a hot one adds further pressure to IWM and reinforces the mid-cap rotation.
Trader’s Action Plan
The core trade remains long MDY against short IWM, sized to reflect the three-to-one drawdown differential Wednesday established. Entry logic is straightforward: yield spikes hurt IWM disproportionately, and with another hike still a live possibility for late October, the environment does not change until the Fed does. Keep stops tight on the short IWM leg given potential for short-covering bounces. On the single-stock side, MSGE and FBP represent the BofA quality screen in action: cash-flow-driven businesses that do not need rates to fall to perform. Neither requires a macro call to work. They simply require the hike cycle to continue, which, as of this morning, looks like exactly what is coming.